German and Austrian industry faces a new logistics squeeze as ocean carriers cut sailings and on‑time arrivals deteriorate — forcing firms to reroute, pre‑stock or pay up for alternatives. For drivers, dealers and suppliers the result is longer delivery windows, higher freight premiums and greater pressure on just‑in‑time chains that still dominate car manufacture and component supply in both countries.
Reliability collapses, carriers trim capacity
Global container schedule reliability has fallen sharply: Xeneta recorded on‑time arrivals of just 50.6% for September 2026, down markedly from earlier in the year. Carriers are responding with selective blank sailings — Drewry reported 56 blankings planned between week 45 and week 49 (2–8 November to 1–7 December 2026), equal to roughly an 8% cancellation rate on those weeks — a deliberate capacity discipline that tightens space for shippers.
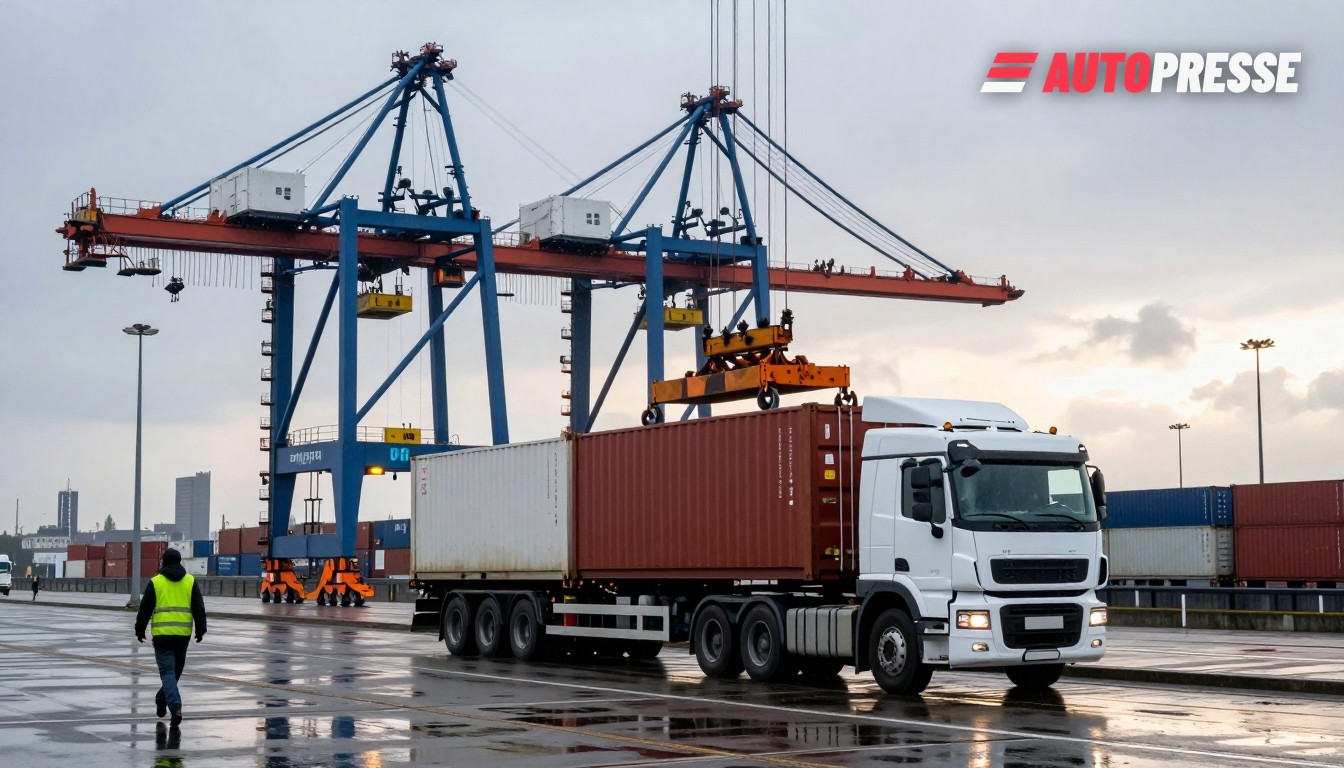
The practical effect is visible at northern European hubs. The Port of Hamburg reported 4.0 million TEU handled in the first half of 2026 and a slight year‑on‑year volume decline for the port overall, while HHLA said container throughput at its Hamburg terminals fell 7.3% year‑on‑year in H1 2026 — signs that flows and scheduling have become more volatile for German importers.
Austria’s exposure: inland demand, routed via trieste and northern hubs
Austria, which depends on sea‑borne inputs routed through neighbouring ports and intermodal links, is feeling the ripple effects. The Austrian Supply Chain Pressure Index rose into the yellow zone in early October 2026, signalling growing transport stress for manufacturers and trade. Meanwhile southern gateways such as the Port of Trieste have increased volumes — Trieste reported a 3.1% rise in cargo handled January–September 2026 — but success at individual Mediterranean terminals does not yet offset Asia–Europe schedule volatility or the risk of equipment imbalances.