Germany and Austria are seeing a clear revival in the two‑wheeler market in 2026 — and it matters to riders, dealers and urban planners. Germany recorded 173,137 new motorcycle registrations year‑to‑date through September, an increase of 24.2% versus 2025, while Austria’s new motorcycle registrations rose 10.3% in the first nine months of 2026 (241,108 new passenger cars were also registered Jan–Sep in Austria, included here as context for overall vehicle demand). These gains are concentrated not only in classic motorcycles but in light classes and electrified two‑wheelers, changing stock profiles and aftersales needs across both countries.
Where growth is coming from
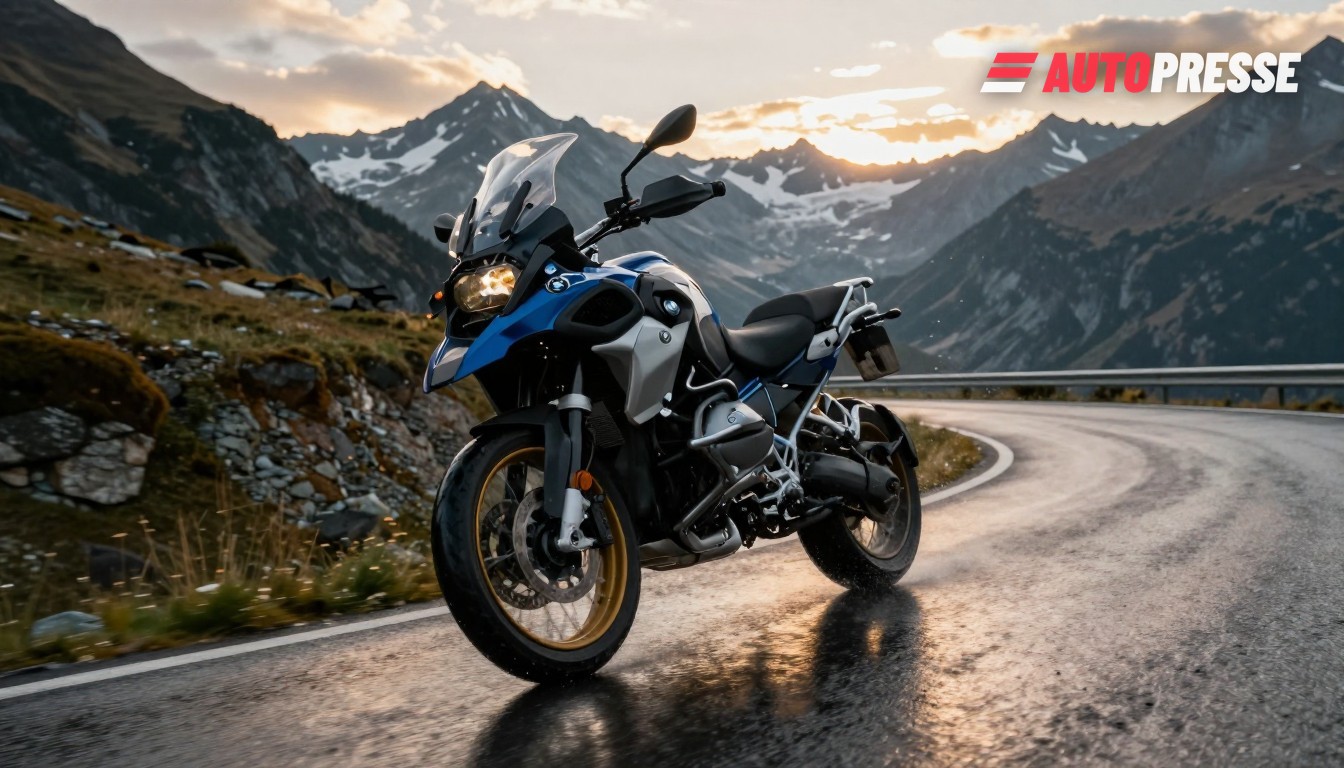
The German increase is driven by higher new‑bike registrations and continued resale activity: the Industrieverband Motorrad (IVM) reports that the market to date is up sharply, with the Vespa GTS 310 and the BMW R 1300 GS among the models topping monthly lists. At the same time, Germany’s official KBA data and industry compilations show that light classes (125‑cc equivalents and scooters) and leisure motorcycles led much of the rise in 2026.
In Austria, Statistik Austria records a 10.3% rise in motorcycle new registrations for January–September 2026, with broader growth across vehicle classes and a notable increase in light two‑wheelers. Austria’s vehicle stock figures also confirm a higher base: the national vehicle stock included roughly 671,842 motorcycles at end‑2025, up versus the year before. That growing fleet is already changing workshop demand in Alpine and urban regions.
Electrification: small numbers, big momentum
Electric two‑wheelers remain a small share of the total, but they are the fastest growing segment. IVM‑based reporting shows that purely battery‑electric motorcycles in Germany rose by 63.6% year‑on‑year in September 2026 to 993 new registrations; e‑light motorcycles (125‑class electrics) and electric scooters posted even stronger percentage gains (examples: e‑light Krafträder up ~140% in published IVM breakdowns). Industry trackers note that nearly every growth vector for the market now has an electrified subcomponent, from city commuters to delivery fleets.
What this means for the market
For dealers: stock and sales strategies must adapt. Rising new‑bike volumes plus faster adoption of e‑light vehicles mean more short‑turn inventory in urban showrooms, new parts for electric drive systems and an increasing share of lower‑margin scooters and 125‑class models. For workshops and training centres: technicians will need competency in high‑voltage systems and battery repair, but much of the immediate aftersales work remains conventional (brakes, tyres, chassis). For fleets and last‑mile operators: electrified scooters and light motorcycles offer lower running costs and regulatory advantages in low‑emission zones — and the data show operators are already adding such vehicles in both countries. For policy and infrastructure: the increase puts pressure on charging and secure parking in city centres and on Alpine tourist routes where motorbike tourism matters.
The motorcycle revival in 2026 is not a return to the pre‑pandemic boom in volumes, but it is a material shift: meaningful growth, faster electrification off a low base, and changing dealer‑workshop economics across Germany and Austria. Market participants should plan for a larger, more diverse two‑wheeler fleet and reallocate sales, training and public‑infrastructure priorities accordingly.
Motorcycle and two-wheeler inventory for dealers on WorldTrader24 →
Sources: Industrieverband Motorrad (IVM), Statistik Austria, Carzoom, SteckerBiker